
Allocated vs. Unallocated Gold Storage & ETF Counterparty Risk: Evaluating Vault Audits, Custody Fees, and Redemption Mechanics
An institutional comparison of allocated segregated bullion, unallocated pool accounts, and paper gold ETFs, detailing legal title, balance-sheet creditor risk, custody fee drag, and physical bar redemption hurdles.
What Is the Difference Between Allocated and Unallocated Gold Storage?
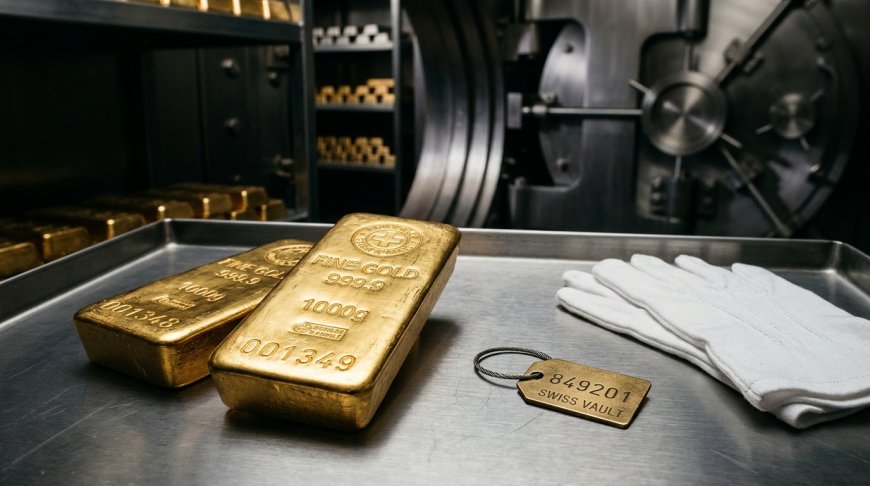
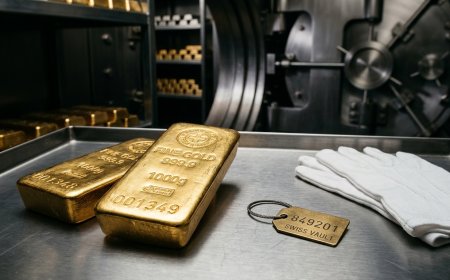
In allocated gold storage, you hold direct legal title to specific, serialized physical bars segregated in a vault under your name, carrying zero bank balance-sheet risk. In unallocated gold, you are an unsecured general creditor to a bullion bank or dealer holding a paper claim against a pooled reserve.
Why Ownership Structure Matters More Than Spot Price During Crises
Investors accumulate gold bullion primarily as tail-risk insurance against sovereign debt stress, banking insolvency, and fiat currency debasement. Ironically, millions of investors purchase that "crisis insurance" through unallocated pool accounts, synthetic futures, or multi-layered Exchange-Traded Funds (ETFs) that reintroduce the exact financial counterparty risk gold is meant to eliminate.
When a bullion dealer or custodial bank operates smoothly, allocated bars, unallocated pool claims, and ETF shares all track the London Bullion Market Association (LBMA) spot price within basis points. The structural divergence occurs during acute liquidity freezes or custodian insolvency: legal title determines whether your metal is ring-fenced property returned to you intact—or frozen inside bankruptcy proceedings alongside unsecured depositors.
"If you do not hold a serialized bar list with explicit bailment title—or direct physical possession—you do not own gold; you own a financial promise linked to the price of gold."
Legal Mechanics: Bailment Title vs. Unsecured Creditor Claims
Under commercial law, Allocated Segregated Storage operates as a bailment contract. You retain outright legal ownership of specific bars (for example, LBMA Good Delivery 400-oz bars or 1-kg 999.9 fine bars) identified by refiner stamp, weight, assay fineness, and serial number. The vault operator acts strictly as a bailee—it cannot lease, rehypothecate, or pledge your bars as collateral, and the metal never sits on the vault's corporate balance sheet.
By contrast, Unallocated Gold Accounts treat metal like a standard bank checking deposit. The dealer owes you a quantity of ounces on demand, uses the pooled metal to finance its own trading inventory or lease market, and records your holding as an unsecured liability. While storage fees are often marketed as "0% free storage," you absorb hidden insolvency risk in exchange for avoiding custody fees.
Live Physical Bullion Valuation & Custody Benchmark
Adjust the interactive sliders and parameters below to calculate real-time figures for this scenario:
Evaluating Paper Gold ETFs: Sub-Custodians & Authorized Participants
Physically backed gold ETFs (such as major London-vaulted trusts) sit in a hybrid middle ground. The trust holds allocated 400-oz London Good Delivery bars on behalf of shareholders, eliminating retail storage friction and offering instant brokerage liquidity. However, institutional due diligence reveals three structural constraints:
- No Retail Physical Redemption: Individual investors cannot redeem ETF shares for physical bars; only institutional Authorized Participants (major bullion banks) can create or redeem baskets—typically in minimum blocks of 50,000 to 100,000 shares (representing 5,000+ ounces).
- Sub-Custodian Chains: Prospectus fine print often allows the primary custodian to appoint sub-custodians during peak vault congestion, and sub-custodian holdings may temporarily sit unallocated during bar settlement windows.
- Expense Ratio Compounding: A 0.40% annual ETF expense ratio steadily erodes the gold-per-share backing each year, reducing long-term metal weight compared to zero-expense home storage or low-fee segregated vaulting.
Institutional Comparison: Storage Models, Fees & Counterparty Exposure
The matrix below compares the four primary methods of holding investment-grade gold across legal title, annual custody drag, liquidity, and physical redemption mechanics:
| Custody Structure | Legal Ownership & Title | Counterparty / Bankruptcy Risk | Typical Annual Fee Drag | Physical Redemption Threshold |
|---|---|---|---|---|
| Home / Private Safe (24K Bars/Coins) | Direct Physical Possession | Zero Financial Counterparty (Theft/Insurance Risk) | 0.00% (1%–3% Buy/Sell Spread) | Immediate (Already Held) |
| Allocated Segregated Vault (Non-Bank) | Direct Bailment Title (Serialized Bar List) | Minimal (Ring-Fenced Off Balance Sheet) | 0.12% – 0.45% / year (Incl. Insurance) | 100g, 1 kg, or 10-tola bars on request |
| Physically Backed Gold ETF | Beneficial Trust Share (No Direct Bar Title) | Low-Moderate (Custodian / Sub-Custodian Chain) | 0.15% – 0.40% Expense Ratio | Institutional Only (5,000+ oz Baskets) |
| Unallocated Pool / Bank Gold Account | Unsecured General Creditor Claim | High (On Dealer/Bank Balance Sheet) | 0.00% – 0.15% (Hidden Lease Risk) | Requires conversion fee + fabrication |
Calculating Total Custody Drag Over a 10-Year Horizon
When comparing a physical coin/bar purchase (2.5% upfront dealer premium, 0% annual fee) against a 0.40% gold ETF or 0.35% allocated vault, investors must model the multi-year crossover point:
Total 10-Year Cost (%) = Upfront_Spread_% + (Annual_Custody_Fee_% * Years_Held)
For a 2-year tactical trade, a 0.40% ETF costs only 0.80% total—far cheaper than paying a 2.50% physical retail spread. Over a 15-year generational hold, however, the ETF's compounding 0.40% fee extracts ~5.8% of your metal weight, making direct physical bullion or low-cost wholesale allocated vaulting (0.12%–0.18% at institutional tiers) mathematically superior.
Basel III & The Re-Pricing of Unallocated Bullion Liquidity
Global banking regulations under Basel III Net Stable Funding Ratio (NSFR) rules fundamentally altered the economics of unallocated gold trading for bullion banks. Previously, commercial banks treated unallocated gold positions as cheap, liquid inventory with minimal capital charges. Under NSFR implementation, unallocated precious-metal liabilities require an 85% Required Stable Funding (RSF) charge—making paper bullion balance-sheet expansion dramatically more expensive for clearing banks.
By contrast, physical allocated gold held off-balance-sheet carries zero NSFR funding penalty for the client and sits cleanly outside fractional-reserve clearing chains. For family offices and treasury desks allocating 5% to 15% of reserves into precious metals as sovereign tail-risk insurance, segregated bailment storage removes both Basel III bank-funding friction and legal-title ambiguity.
5-Point Bullion Custody & Vault Audit Checklist
- Demand Serialized Bar Lists Quarterly: Never accept a generic statement showing "100 oz Fine Gold" without corresponding refiner hallmarks, gross weights, and unique bar serial numbers assigned to your account.
- Verify Third-Party Physical Audits: Confirm the vault operator publishes independent, unannounced physical inspection reports from recognized assayers (such as Bureau Veritas, Inspectorate, or specialized Big-Four audit teams) rather than internal self-attestations.
- Check Insurance Underwriting & All-Risk Limits: Ensure Lloyd's of London or equivalent all-risk bullion insurance covers 100% of total vaulted market value—not a capped per-incident limit that leaves clients underinsured during price surges.
- Prefer Non-Bank Independent Vaults Outside Your Home Jurisdiction: Storing allocated bars in non-bank facilities (e.g., Zurich, Singapore, or independent domestic depositories) decouples metal custody from commercial banking fractional-reserve stress.
- Confirm Transparent Exit & Assay Fabrication Fees: Read the fee schedule for physical bar delivery—verify shipping, armored courier insurance, and fabrication charges before funding the account so you are never trapped by surprise exit penalties.









Comments