
The 50/30/20 Rule in High-Inflation Economies: Adapting the Classic Budget Framework for Modern Living Costs
Discover how to calibrate the classic 50/30/20 budget framework in high-inflation environments. Learn realistic adaptation ratios (60/20/20 and 55/25/20) to balance rising essentials with long-term wealth building.
 Elena Vance, CFP®
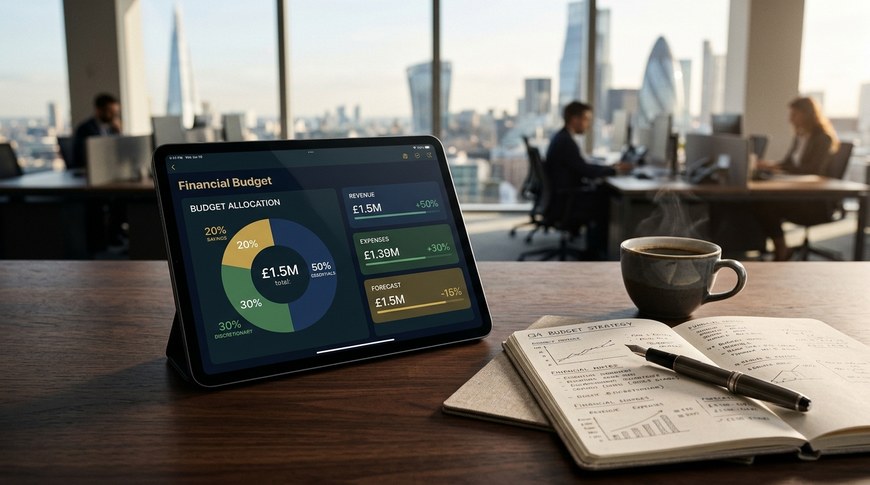
The classic 50/30/20 budgeting framework—popularized by Senator Elizabeth Warren and financial planner Amelia Warren Tyagi—has long stood as one of personal finance's most intuitive and elegant guidelines. By designating 50% of after-tax income to essential needs, 30% to discretionary wants, and 20% to savings and debt reduction, millions of households established disciplined financial foundations. However, prolonged inflationary pressures across shelter, groceries, healthcare, and energy have fundamentally altered household cost baselines, leading many to question whether the traditional 50/30/20 formula remains viable in modern economic conditions.
When living essentials consistently consume 60% or more of net take-home pay, adhering strictly to a rigid 50% needs ceiling often triggers guilt, financial fatigue, and abandonment of budgeting entirely. In this comprehensive guide, we examine the macroeconomic mechanics squeezing traditional allocations and present calibrated, mathematically sound adaptations that preserve your wealth-building trajectory without forcing unrealistic lifestyle deprivation.
1. The Structural Squeeze: Why 50% for Needs Is Breaking Down
To understand why the conventional ratio feels unattainable in contemporary urban centers, one must analyze where inflation concentrates. Unlike broad CPI measures, essential living expenses—frequently termed "non-discretionary inflation"—have risen at structural rates significantly outpacing nominal wage growth over recent multi-year cycles.
| Expense Category | Historical Benchmark (% of Net) | Current High-Inflation Baseline (% of Net) | Primary Economic Drivers |
|---|---|---|---|
| Housing & Utilities | 25% – 30% | 35% – 45% | Mortgage rate locks, tight rental inventory, elevated insurance premiums |
| Food at Home (Groceries) | 10% – 12% | 14% – 18% | Supply chain reshoring, agricultural input costs, geopolitical pressures |
| Transportation & Auto | 10% – 12% | 12% – 16% | Vehicle replacement costs, elevated financing rates, maintenance surges |
| Healthcare & Insurance | 5% – 8% | 8% – 12% | Medical services inflation, rising deductible minimums |
When these core categories compound, baseline survival costs naturally swell toward 60% to 65% of net income. For households earning median incomes in tier-1 and tier-2 metropolitan areas, insisting on a 50% ceiling is not merely difficult—it is mathematically incompatible with basic survival requirements.
2. Calibrated Budget Models: 60/20/20 and 55/25/20
Rather than discarding structured financial planning, pragmatic households adjust the allocation dials to reflect realistic market realities while strictly ring-fencing the most critical financial health metric: the 20% savings rate.
Model A: The 60/20/20 Inflation-Adaptive Framework
In this model, the 10% overflow in essential expenditures is absorbed entirely by discretionary lifestyle spending rather than cutting savings contributions:
- 60% Needs (Essential Baseline): Rent/mortgage, minimum debt payments, utilities, basic groceries, core transportation, and healthcare.
- 20% Wants (Discretionary Consumption): Dining out, subscription entertainment, gym memberships, hobbies, and leisure travel.
- 20% Wealth Building (Uncompromised Future): Emergency fund reserves, 401(k) / IRA retirement contributions, high-interest debt acceleration, and index fund investing.
Model B: The 55/25/20 Balanced Cushion
For individuals in moderate cost-of-living areas or those who have successfully negotiated lease renewals, the 55/25/20 structure provides a gentle middle ground that allows sustainable lifestyle flexibility while continuing to outpace future currency debasement.
Run Your Exact Numbers Instantly
Calculate your custom needs, wants, and savings allocations based on your take-home pay using our interactive RichQuill 50/30/20 Budget Calculator →. Instantly toggle between 50/30/20, 60/20/20, and custom allocation ratios.
3. Categorization Traps: Separating True Needs from Elevated Wants
During inflationary periods, lifestyle creep frequently disguises itself as essential expenditure. Rigorous budget governance requires auditing transactions through an unsparing classification lens:
- The Smartphone & Connectivity Test: Reliable cellular service and high-speed home internet are undeniable professional and logistical necessities. However, carrying an unlimited premium plan with subsidized annual device upgrades belongs in the wants tier. Transitioning to mobile virtual network operators (MVNOs) frequently reduces this line item by 60% without sacrificing coverage.
- Nutritional Sustenance vs. Convenience Dining: Nutrient-dense whole groceries represent non-negotiable living essentials. Conversely, pre-packaged specialty convenience foods, artisanal beverages, and meal kit delivery services constitute convenience upgrades that properly reside in discretionary spending.
- Transportation Utility: Reliable commuting transportation to secure earned income is a strict need. Financing an upscale crossover vehicle with a $750 monthly payment and $250 insurance obligation when a certified pre-owned commuter car would fulfill the utilitarian function is a lifestyle choice.
4. Preserving the 20% Wealth Building Engine
The cardinal error budgeters make when costs rise is treating the 20% savings and investment bucket as a flexible shock absorber. Sacrificing compound interest during inflationary cycles inflicts permanent long-term damage on retirement horizons. Because inflation erodes the future purchasing power of currency, owning productive equities and compounding yield-bearing assets is more critical during inflationary regimes than in benign deflationary eras.
If acute emergency circumstances temporarily force a reduction below 20%, establish a non-negotiable step-up timeline: commit 50% of every subsequent performance bonus, tax refund, or merit salary increase directly to automated savings until the 20% threshold is restored.
Frequently Asked Questions (FAQ)
Should minimum debt payments be counted in Needs or Savings?
Contractual minimum debt service payments (such as student loans or auto payments) must be categorized under Needs, because defaulting irreparably harms creditworthiness and incurs legal consequences. Any accelerated principal payments above the required minimum should be recorded under the 20% Savings/Debt Payoff bucket.
What if my essential expenses exceed 70% of my income?
When baseline needs exceed 70%, budgeting adjustments alone cannot bridge the gap. At this threshold, strategic structural interventions are required: exploring relocation to lower-cost housing, taking on shared living arrangements, or prioritizing high-leverage skill acquisition and career transitions to expand gross top-line earnings.








Comments