
Treasury Yield Curve Inversion (10Y-2Y): Historical Lead Times, Term Premiums, and Liquidity Traps
An institutional analysis of Treasury yield curve inversions, disinversion mechanics, historical recession lead times, and monetary transmission lag effects.
The Most Accurate Recession Warning Engine in Macroeconomic History
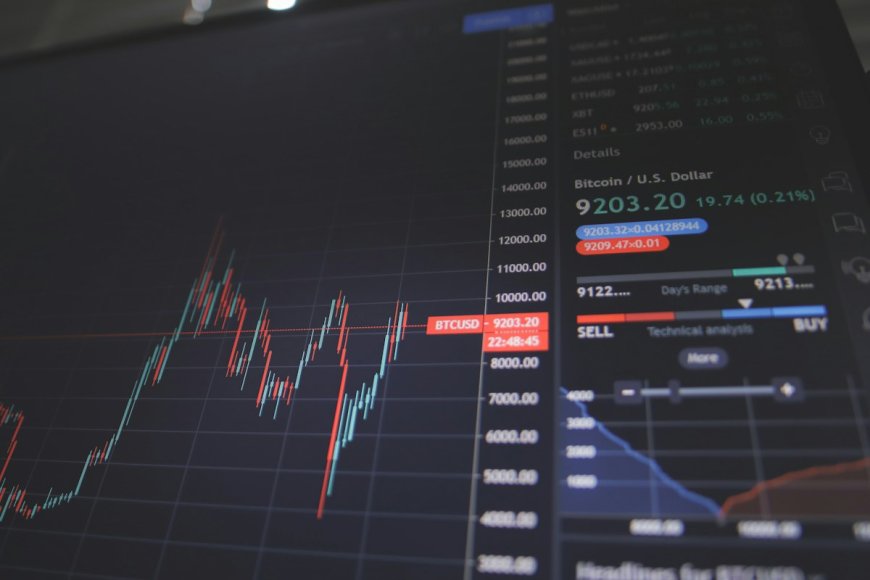
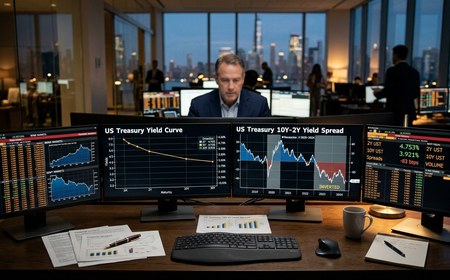
In fixed-income portfolio management and macroeconomic forecasting, the shape of the sovereign government bond yield curve serves as the most dependable empirical leading indicator of business cycle transitions. Under normal, expansionary market regimes, the yield curve slopes upward: investors demand a higher yield (term premium) to lock up capital in 10-year or 30-year paper compared to short-dated 3-month or 2-year bills to compensate for duration and inflation risk.
However, when the Federal Reserve raises benchmark interest rates to cool inflationary pressure while financial markets foresee an inevitable economic contraction, short-term yields surge above long-term yields. This phenomenon—known as an Inverted Yield Curve, specifically measured through the spread between the 10-Year and 2-Year Treasury yields ($10Y - 2Y$) or the 10-Year and 3-Month yields ($10Y - 3M$)—has preceded every single US economic recession since 1955, producing only one false positive in over 70 years of market data.
"The bond market is never fooled by equity market optimism. When long-term yields collapse below short-term rates, capital is declaring that future growth will be weaker, corporate earnings will compress, and the central bank will be forced to cut rates."
The Dangerous Paradox: The "Un-Inversion" Trigger
A widespread misconception among retail investors is the assumption that the economic crisis occurs while the yield curve remains deeply inverted. In reality, historical empirical data reveals the opposite: recessions almost never begin during the inversion itself. The equity market frequently rallies while the curve is inverted.
The true danger zone arrives during the Disinversion (Un-Inversion) Phase. When the central bank recognizes structural labor market softening or financial liquidity cracks, it abruptly slashes short-term policy rates. Short-term yields plummet faster than long-term yields (a Bull Steepener), steepening the curve back into positive territory. Historically, the onset of recession and severe equity market drawdowns occurs within 2 to 8 months of the curve's re-steepening.
| Historical Inversion Date | Peak Negative Spread (bps) | Un-Inversion Date | NBER Recession Start | Total Lead Time (Months) |
|---|---|---|---|---|
| August 1978 | -241 bps | May 1979 | January 1980 | 17 Months |
| December 1988 | -45 bps | October 1989 | July 1990 | 19 Months |
| February 2000 | -52 bps | December 2000 | March 2001 (Dot-Com) | 13 Months |
| December 2005 | -24 bps | June 2007 | December 2007 (GFC) | 24 Months |
| July 2022 – 2024 Cycle | -108 bps (Deepest in 40 Yrs) | September 2024 | Active Cycle Monitoring | Historic Long Lag Era |
Contextual Tool: Track Yield Differentials
Benchmark current sovereign interest rate yields and analyze the spread dynamics across global fixed income benchmarks:
Sovereign Yield Spread & Curve Inversion Engine
Adjust the interactive sliders and parameters below to calculate real-time figures for this scenario:
The Monetary Transmission Mechanism: Why the Lag Occurs
The 12-to-24 month operational lag between initial inversion and real economic contraction is governed by three institutional transmission stages:
- Corporate Debt Buffers: Large-cap corporations lock in multi-year fixed-rate debt during low-interest periods. High central bank policy rates do not immediately impair their balance sheets until debt tranches mature and require refinancing at higher coupons.
- Banking Credit Contraction: Inverted yield curves render the commercial banking model (borrowing short via deposits to lend long via mortgages and business loans) structurally unprofitable, causing lenders to tighten underwriting standards and contract credit supply.
- Labor Market Capitulation: Corporate executives initially respond to tight credit by cutting discretionary capital expenditures. Only when revenue growth softens does management initiate layoffs, triggering the consumer demand contraction that officially defines a recession.
The Bull Steepener vs. Bear Steepener Dynamic
Not all yield curve un-inversions are identical. A Bull Steepener occurs when the Fed slashes short rates due to economic weakness (the historical recession harbinger). A Bear Steepener occurs when long-term rates surge due to inflation concerns or excessive sovereign debt issuance.
Executive FAQ: Treasury Yield Curves
How should an investor position a portfolio during an inverted yield curve?
Investors typically extend duration in high-quality fixed income to lock in yields before rate cuts occur, while maintaining defensive allocations in cash sweeps and bullion.
Institutional Governance & Multi-Horizon Sensitivity Modeling
To ensure balance sheet durability across macroeconomic cycles, corporate directors and chief financial officers mandate periodic sensitivity stress-testing. Rather than relying exclusively on baseline forecasts, prudent capital allocators model performance across three discrete economic regimes: the Base Case (consensus market expectations), the Downside Stress Scenario (incorporating a 25% revenue compression, a 200 bps adverse interest rate shift, or elevated counterparty default rates), and the Counter-Cyclical Expansion Scenario.
By pre-calculating these financial boundaries, enterprise leadership eliminates emotional decision-making during market panics. Capital reserves are deployed with quantitative discipline, ensuring that liquidity buffers remain funded while competitor organizations struggle with refinancing constraints or operational cash shortages.
| Macroeconomic Regime | Assumed Volatility Factor | Cash Flow Impact | Operational Strategy Trigger |
|---|---|---|---|
| Expansionary Environment | +15% Growth; Low Borrowing Spreads | Maximum cash accumulation; elevated margins | Automate dividend sweeps and accelerate long-term capital investments |
| Stagflationary Pressure | 3.5%+ Inflation; Flat Demand | Cost of goods sold surges; margin compression | Enforce strict contractual price escalation clauses and trim low-margin product lines |
| Severe Liquidity Contraction | -25% Demand; Frozen Credit Lines | Rapid burn escalation; receivables collection delays | Deploy dedicated secondary liquidity buffers; pause all non-essential capital expenditures |
Executive Implementation Roadmap & Quarterly Audit Cadence
Executing this framework with consistent institutional rigor requires embedding structured review protocols into your monthly and quarterly financial cadence:
- Day 1 – Day 5 (Monthly Close Reconciliation): Audit actual cash burn, collection velocity, and margin variances against budgeted models. Identify any line-item cost increases exceeding 5% and eliminate non-essential software or service subscriptions immediately.
- Day 15 (Mid-Month Treasury Review): Re-evaluate accounts receivable aging reports. Enforce credit holds on enterprise accounts that cross 45 days past due, and offer 1.5% instant settlement discounts for electronic clearing.
- Quarterly Board Review (Governance Audit): Recalculate your baseline metrics (WACC, CCC, LTV:CAC, or SWR) incorporating the most recent 90-day trailing data. Present a formal sensitivity variance report to board members or investment committees to confirm balance sheet resilience.
- Annual Capital Structure Rebalancing: Realign debt-to-equity ratios, review banking credit facilities, and execute strategic tax deductions before the close of the fiscal year to maximize retained capital.
Quantitative Regulatory Governance & Institutional Compliance
In mature corporate governance and portfolio risk management, financial leaders must align operational execution with international accounting standards (IFRS 15 for revenue recognition, IFRS 16 for lease capitalization) and Basel III/IV capital adequacy frameworks. When deploying balance sheet resources, management must establish strict internal controls, including dual-authorization signing thresholds on bank disbursements, automated continuous transaction auditing, and transparent reporting to audit committees.
Furthermore, maintaining high compliance standards safeguards corporate enterprise value during mergers, acquisitions, and private equity due diligence. Investors and institutional lenders consistently assign premium valuation multiples to organizations demonstrating disciplined financial controls, transparent working capital management, and robust liquidity planning.
- Automated Ledger Verification: Reconcile merchant processing accounts, inventory valuation ledgers, and accounts payable bi-weekly to prevent hidden accounting drift.
- Covenant Compliance Monitoring: Track bank debt covenants—including minimum debt-service coverage ratios (DSCR ≥ 1.35x) and fixed charge coverage—in real time to avoid technical covenant defaults.
- Tax Shield Optimization: Leverage accelerated depreciation (Section 179 and MACRS bonus depreciation) alongside R&D payroll tax credits to minimize corporate tax drag and retain valuable operating cash flow.









Comments