
How to Calculate Zakat on 401(k), RSU Stocks & Bullion: 2026 Nisab Threshold Guidelines
An authoritative guide to calculating Zakat on modern equities, RSUs, 401(k) accounts, and bullion based on classical jurisprudence and current gold/silver Nisab values.
The Modern Juristic Challenge: Evaluating Contemporary Financial Instruments
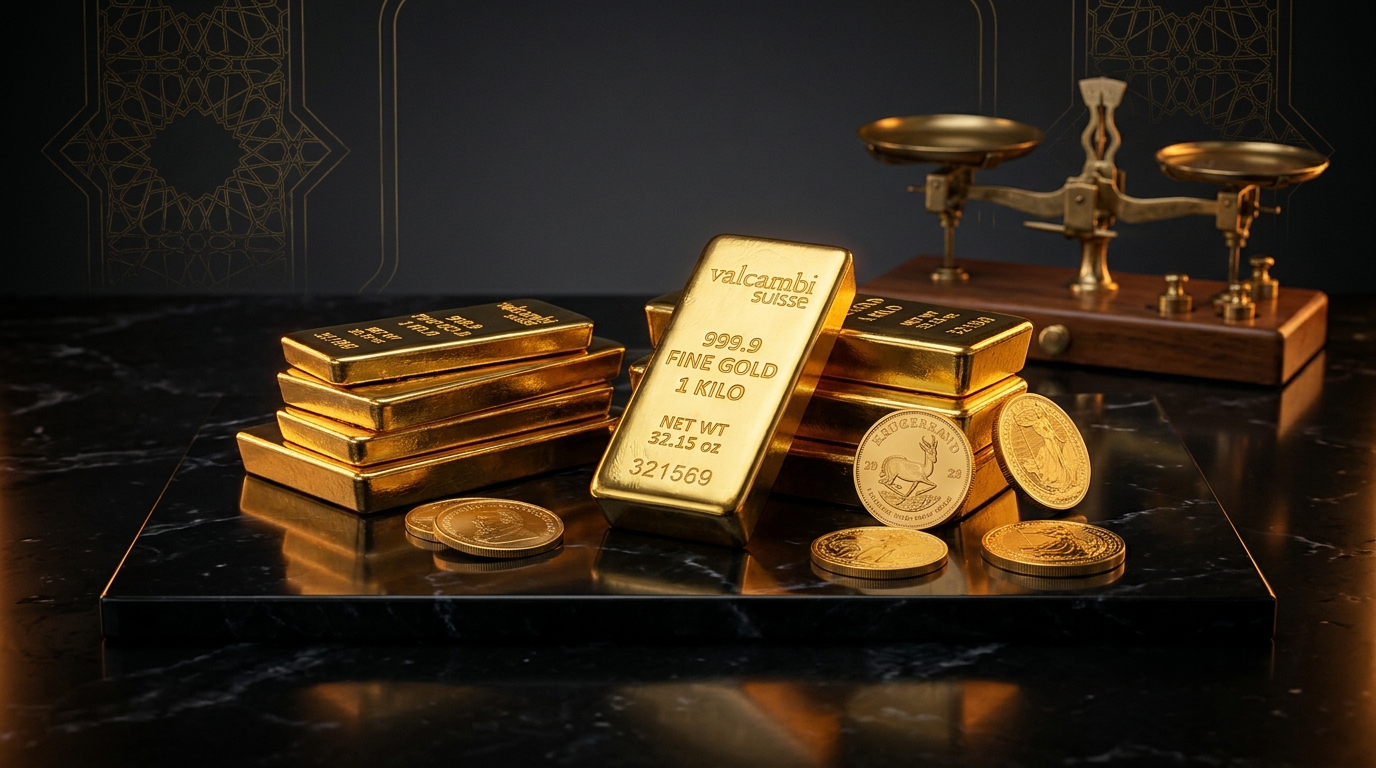
In Islamic financial jurisprudence (Fiqh al-Mu'amalat), Zakat is an obligatory annual religious levy of 2.5% assessed on qualifying surplus wealth (*Amwal Zakawiyyah*) held for a complete lunar year (*Hawl*), provided total net worth exceeds the foundational threshold known as Nisab. Classical juristic scholarship codified Nisab based on two primary commodity standards: 20 Dinars of Gold (equivalent to 85 grams or 7.28 Tolas of 24K gold) and 200 Dirhams of Silver (equivalent to 595 grams of pure silver).
However, the explosive proliferation of complex modern asset classes—including deferred employer retirement accounts (401(k), 403(b)), Restricted Stock Units (RSUs), and synthetic market derivatives—presents contemporary high-net-worth professionals with complex valuation questions. Applying a blanket 2.5% levy on gross unvested equity or tax-penalized retirement balances creates punitive double taxation that violates the Islamic legal maxim of equity (*Adl*).
"Modern corporate wealth consists of future vesting promises and government-penalized deferred accounts. Zakat is due exclusively upon wealth over which the believer possesses full, actionable ownership and unrestricted disposal rights (Al-Milk al-Tamm)."
The Fiqh Framework for Equities, RSUs, and Retirement Funds
Contemporary scholars from the Fiqh Council of North America (FCNA) and the Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI) recognize three distinct asset treatments:
| Asset Category | Ownership Status | Valuation Methodology for Zakat | Levy Rate |
|---|---|---|---|
| Physical Gold & Silver Bullion | Full Immediate Possession | Current spot market rate × total grams (if ≥ 85g gold) | 2.50% (Lunar) / 2.577% (Solar) |
| Public Equities (Short-Term Trading) | Trade Inventory (*Urud al-Tijarah*) | 100% of Fair Market Value (FMV) on Zakatable anniversary date | 2.50% |
| Public Equities (Passive Long-Term) | Dividend / Capital Appreciation | Rule of Thumb: 25% to 30% of market value (representing underlying liquid working capital) | 2.50% of the 30% proxy (~0.75% of total value) |
| Vested 401(k) / Traditional IRA | Encumbered / Tax-Penalized | Gross Account Value minus (Mandatory Ordinary Income Tax + 10% Early Withdrawal Penalty) | 2.50% on Net Liquid Realizable Value |
| Unvested RSUs / Stock Options | Non-Possessed / Contingent | $0 (Zero Zakat due until formal vesting and delivery occurs) | Exempt until vested |
Contextual Calculation: Compute Your Exact Annual Obligation
Utilize our specialized live Zakat computation module to aggregate your cash reserves, bullion holdings, and discounted equity assets against real-time Nisab benchmarks:
Institutional Zakat & Nisab Threshold Modeler
Adjust the interactive sliders and parameters below to calculate real-time figures for this scenario:
Practical Execution: The 4-Step Annual Zakat Audit
- Establish a Permanent Hijri Valuation Date: Select a consistent lunar date (such as the 27th of Ramadan or 1st of Muharram) to calculate your balance sheet annually.
- Benchmark the Live Nisab: Determine the current market price of 85 grams of 24K gold. If total net zakatable assets fall below this dollar figure, no Zakat is due.
- Apply Net Working Capital Proxies for Long-Term Portfolios: Rather than liquidating shares to pay 2.5% on heavy plant, equipment, and intellectual property owned by public corporations, apply the recognized 30% liquid asset proxy across broad index funds (VTSAX, SPY).
- Disburse to Recognized Asnaf Categories: Route disbursements directly to verified local welfare organizations or global humanitarian initiatives addressing the eight Quranic categories of recipients specified in Surah At-Tawbah (9:60).









Comments