
The Corporate Debt Maturity Wall: Refinancing Risk, Yield Curve Inversion, and High-Yield Spread Dynamics
A macroeconomic investigation into the multi-trillion-dollar corporate refinancing wall, dissecting maturity clustering, coupon repricing shocks, and balance sheet resilience.
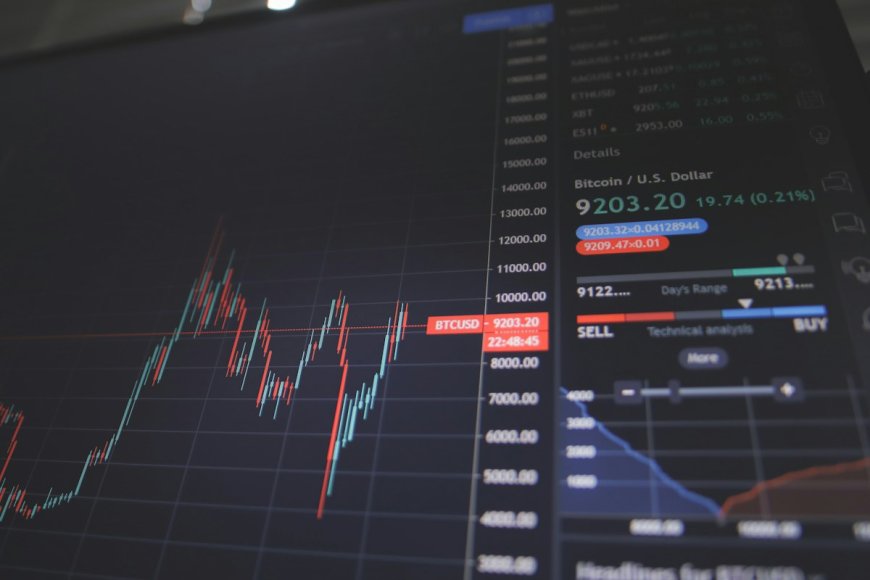
Throughout the prolonged era of Zero Interest Rate Policy (ZIRP) and quantitative easing following the 2008 global financial crisis, international corporations capitalized upon historically unprecedented debt market liquidity. Investment-grade conglomerates and speculative-grade (high-yield) enterprises aggressively issued fixed-rate corporate bonds and syndicated loans at nominal coupons ranging between 2.5% and 4.5%. However, as global central banks enacted the most aggressive interest rate hiking cycle in four decades to combat secular inflation, the macroeconomic landscape underwent a violent structural paradigm shift. Today, global capital markets confront a monumental challenge: the impending Corporate Debt Maturity Wall.
The Architecture of the Refinancing Cliff
The debt maturity wall represents the aggregate volume of corporate debt instruments scheduled to mature within an upcoming chronological window that must either be redeemed from liquid operational cash balances or refinanced in contemporary credit markets at prevailing benchmark yields. Between 2025 and 2028, over $2.8 trillion in US corporate debt and approximately €1.6 trillion in European enterprise obligations will reach contractual maturity.
For investment-grade borrowers, refinancing implies a painful but manageable contraction of operating margins as debt service doubles from 3.0% to 6.0%. However, for speculative-grade companies (rated BB and below) and private equity-backed portfolio companies capitalized with floating-rate leveraged loans, the coupon repricing shock threatens basic operational solvency:
Example: An enterprise refinancing $500,000,000 in senior notes from 3.75% to 8.25% experiences a $22,500,000 annual surge in pre-tax interest overhead.
Corporate Amortization & Debt Service Model
Calculate the debt service payment surge when floating-rate facility or maturing corporate bond resets from zero-rate era coupons to contemporary yields:
Yield Curve Inversion: Mechanics and Recessionary Predictive Power
Simultaneously complicating corporate capital planning is the persistent inversion of the sovereign yield curve—where short-term Treasury bill yields (e.g., 3-month and 2-year notes) yield higher nominal returns than long-duration 10-year and 30-year sovereign bonds. Historically, the inversion of the 10-Year vs. 2-Year Treasury spread (\(10Y - 2Y < 0\)) has served as the single most reliable macroeconomic leading indicator of cyclical economic contraction across the post-war era:
| Historical Inversion Epoch | Initial Inversion Date | Subsequent Recession Start | Lag Duration (Months) | High-Yield Spread Peak |
|---|---|---|---|---|
| Dot-Com Bubble | February 2000 | March 2001 | 13 Months | 980 bps (9.80%) |
| Great Financial Crisis | December 2005 | December 2007 | 24 Months | 2,180 bps (21.80%) |
| Global Pandemic | August 2019 | February 2020 | 6 Months | 1,080 bps (10.80%) |
| Post-Pandemic Inflation Era | July 2022 | Extended Disinflation Cycle | Ongoing Compression | Monitored Spread Range |
The Disinversion Catalyst: Contrary to popular market perception, recessions historically do not ignite while the yield curve is actively inverted. Rather, financial crises erupt when the curve rapidly un-inverts (steepens) as central banks aggressively cut emergency benchmark rates in response to abrupt labor market deterioration or credit system fractures.
High-Yield Credit Spreads: The Canary in the Corporate Coal Mine
The true barometer of corporate financial stress is not benchmark government bond yields, but rather the Option-Adjusted Spread (OAS) demanded by institutional bond buyers above risk-free sovereign debt. When high-yield spreads trade below 350 basis points (3.5%), corporate credit markets exhibit benign complacency. However, when credit spreads gap above 600 to 800 basis points, access to unsecured commercial paper and high-yield bond syndication abruptly freezes.
Maturity Extension Swaps and Pre-Funding Defensive Playbooks
Prudent corporate treasurers do not wait for the final twelve months of a bond's contractual tenure to address maturity risk. Institutional best practice mandates executing liability management transactions (LMTs) at least 24 to 36 months prior to expiration. These include tender offers, debt-for-debt exchanges, and pre-funding new issuances during temporary credit spread compression windows, locking in liquidity before broad credit market dislocations occur.
Private Credit Disintermediation: Safety Valve or Systemic Shadow Risk?
As traditional commercial banks retreated from leveraged lending under tightened regulatory capital constraints, the global Private Credit market surged past $1.7 trillion. Direct lenders—such as Ares, Blackstone, and Blue Owl—stepped in to refinance maturing syndicated loans for middle-market enterprises unable to access public bond markets. However, private credit facilities typically carry floating interest rates set at 550 to 750 basis points above SOFR, significantly increasing the ongoing debt service burden on operating cash flow.
The Debt Service Coverage Ratio (DSCR) Stress Test Framework
To evaluate refinancing feasibility, institutional creditors deploy the Debt Service Coverage Ratio (DSCR) stress test: \(\text{DSCR} = \text{Net Operating Income} / (\text{Principal} + \text{Interest Debt Service})\). When rising interest rates compress corporate DSCR below 1.25x, lenders enforce restrictive covenants, dividend freezes, or mandatory equity infusions, forcing management into defensive capital preservation postures.
The Zombie Enterprise Shakeout
According to Bank for International Settlements (BIS) estimates, approximately 12% to 15% of publicly traded global corporations operate as "zombie companies"—enterprises whose operating profits (EBITDA) fail to cover contractual debt service expenses (\(\text{ICR} = \text{EBITDA} / \text{Interest Expense} < 1.0\)). For a decade, these entities survived through perpetual low-rate refinancing roll-overs.
As the corporate debt maturity wall arrives in force, the window for artificial balance sheet survival has decisively closed. Enterprises possessing robust free cash flow, flexible capital expenditures, and manageable leverage will acquire distressed assets at substantial discounts, while over-leveraged entities will face restructuring, debt-for-equity swaps, or Chapter 11 liquidations. For macro allocators and corporate leaders, proactive liability extension and capital discipline represent the definitive difference between balance sheet supremacy and insolvency.








Comments